SDIRA Note Default: Survival Guide for Investors
Self-Directed IRAs, Private Lending, Note Defaults
When Your SDIRA Borrower Stops Paying: A Note Default Survival Guide
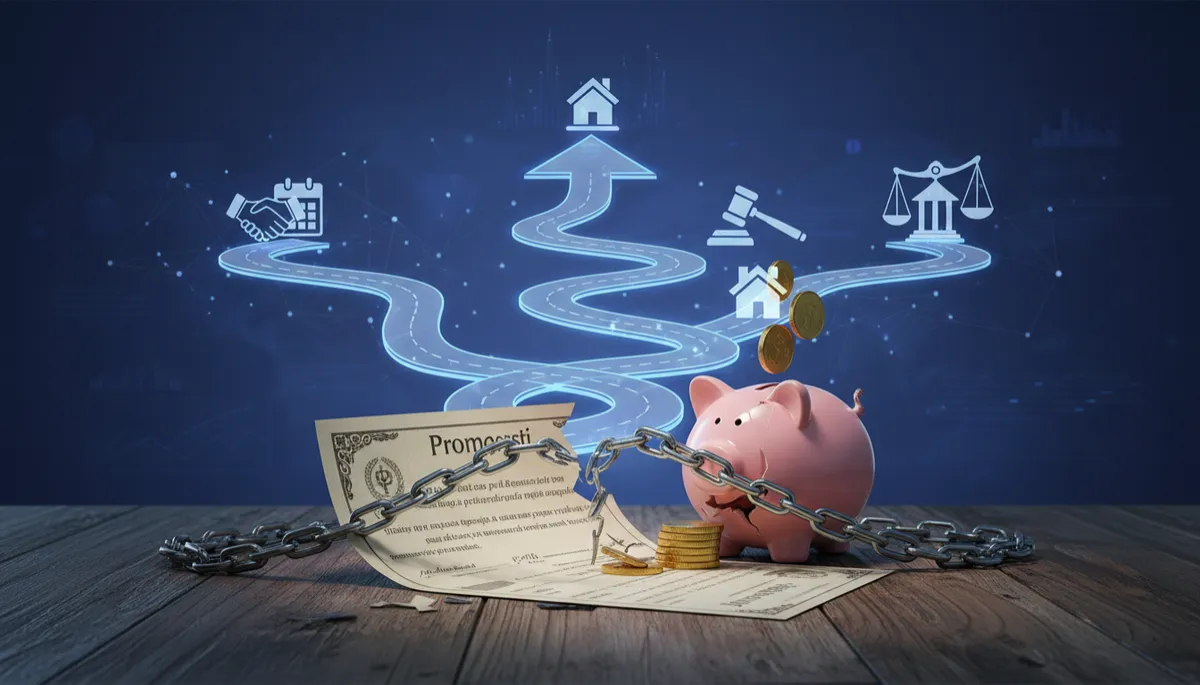
A private lending deal can turn sour even with strong due diligence. This guide walks through what typically happens when a borrower in your self-directed IRA (SDIRA) stops paying, and outlines the three primary paths you can take to protect your retirement capital and move toward resolution.
What “Default” Means for a Self-Directed IRA Note
In private lending, a default is not just a missed payment. It is a specific event defined in your promissory note and related loan documents. For SDIRA investors, those documents should spell out when a payment is considered late, what constitutes an event of default, and what remedies the lender (your IRA) may pursue if the borrower fails to cure the problem within a stated period.
Common triggers include missed monthly payments, failure to pay property taxes or insurance on a secured property, unauthorized transfers of collateral, or bankruptcy filings. Once an event of default occurs under the terms of the note, your IRA—as the lender—typically has the right to accelerate the loan, pursue late fees, and begin collection or foreclosure actions, subject to state law and the loan documents.
The First Phase: Recognizing and Documenting the Default
When a borrower stops paying, your first step is to confirm the facts and review your documents. Because the SDIRA is the actual lender, all actions must be taken in the name of the IRA, not you personally. You, as the account holder, provide direction, but the custodian or administrator will sign documents and process payments on behalf of the IRA when required.
- Review the note and deed of trust or mortgage. Confirm due dates, grace periods, late fees, default provisions, and notice requirements.
- Verify payment history. Compare your records with the custodian’s transaction history to ensure no payments were misapplied or delayed.
- Check the status of collateral. For real estate–backed notes, confirm property taxes, insurance coverage, and occupancy or construction status where applicable.
Once you confirm a default, many loan documents require a notice of default or notice to cure to be sent to the borrower. This notice outlines the missed obligations, the cure amount, and the deadline to bring the loan current. Your attorney can help ensure the notice complies with state law and the loan terms, and your IRA custodian will typically sign and send the notice at your direction.
Three Primary Paths Forward After a Borrower Stops Paying
Once the default is established and documented, SDIRA lenders usually face three broad options. The right path depends on the borrower’s situation, the quality of the collateral, the remaining loan term, and your risk tolerance and time horizon inside the IRA.
Path 1: Work Out a Loan Modification or Forbearance
The first and often least disruptive path is a workout—negotiating new terms that give the borrower a realistic chance to recover while still protecting your IRA. This may include extending the maturity date, temporarily reducing payments, adding missed interest to the principal balance, or adjusting the interest rate in exchange for additional security or guarantees, where permitted.
Any modification must be documented formally, signed by all parties, and processed through your SDIRA custodian. It is critical that you avoid personal involvement in collecting payments or accepting collateral in your own name, as that could create a prohibited transaction. Instead, your role is to evaluate the borrower’s updated financials, assess the collateral, and direct the IRA to accept or reject the proposed modification.
Path 2: Move Toward Foreclosure or Other Legal Remedies
If a workout is not feasible or the borrower is unresponsive, the next path is to pursue your legal rights as a secured lender. For real estate–backed SDIRA loans, this usually means starting a foreclosure process—judicial or nonjudicial, depending on your state and the instrument used (deed of trust or mortgage).
Foreclosure timelines and costs vary widely. You will typically engage a real estate or creditor’s rights attorney, and all legal invoices must be paid from IRA funds, not personal funds. Throughout the process, your custodian signs legal documents on behalf of the IRA and disburses payments from the account at your direction. If the property is ultimately taken back by the IRA at foreclosure sale, the IRA becomes the owner of the asset and may hold, improve, or sell it, subject to SDIRA rules and prohibited transaction restrictions.
In some cases, you may also pursue a deed in lieu of foreclosure or, where appropriate, a negotiated settlement that transfers the collateral to the IRA without a full foreclosure process. Each option has legal and tax considerations, so professional guidance is essential.
Path 3: Sell or Assign the Non-Performing Note
A third path is to sell or assign the defaulted note to another investor who specializes in non-performing loans. This approach may allow your IRA to exit the position more quickly, albeit typically at a discount to the unpaid principal balance. In exchange, you avoid the time, complexity, and uncertainty of a full legal process or long-term workout.
If you choose this path, the note sale must be structured as an IRA-to-third-party transaction. The buyer cannot be you personally or any other disqualified person under IRS rules. The assignment documents will be executed by your custodian on behalf of the IRA, and sale proceeds will flow back into the IRA as cash, ready for redeployment into other investments that align with your strategy and risk profile.
Managing Risk and Expectations Before and After Default
While a default is never welcome, it is a known risk in private lending. The most effective SDIRA investors plan for this possibility long before it occurs. That planning includes conservative loan-to-value ratios, clear documentation, experienced legal counsel, and a realistic understanding of how long workouts and foreclosures can take in the relevant jurisdiction.
When a borrower does stop paying, your objective is to respond methodically rather than emotionally. Confirm the default, understand your rights, evaluate each of the three paths—modification, legal enforcement, or sale of the note—and choose the route that best balances recovery potential, time, and administrative burden for your self-directed IRA. With a disciplined approach and appropriate professional support, a defaulted note can be managed as one chapter in a broader long-term retirement strategy, rather than a defining event.
