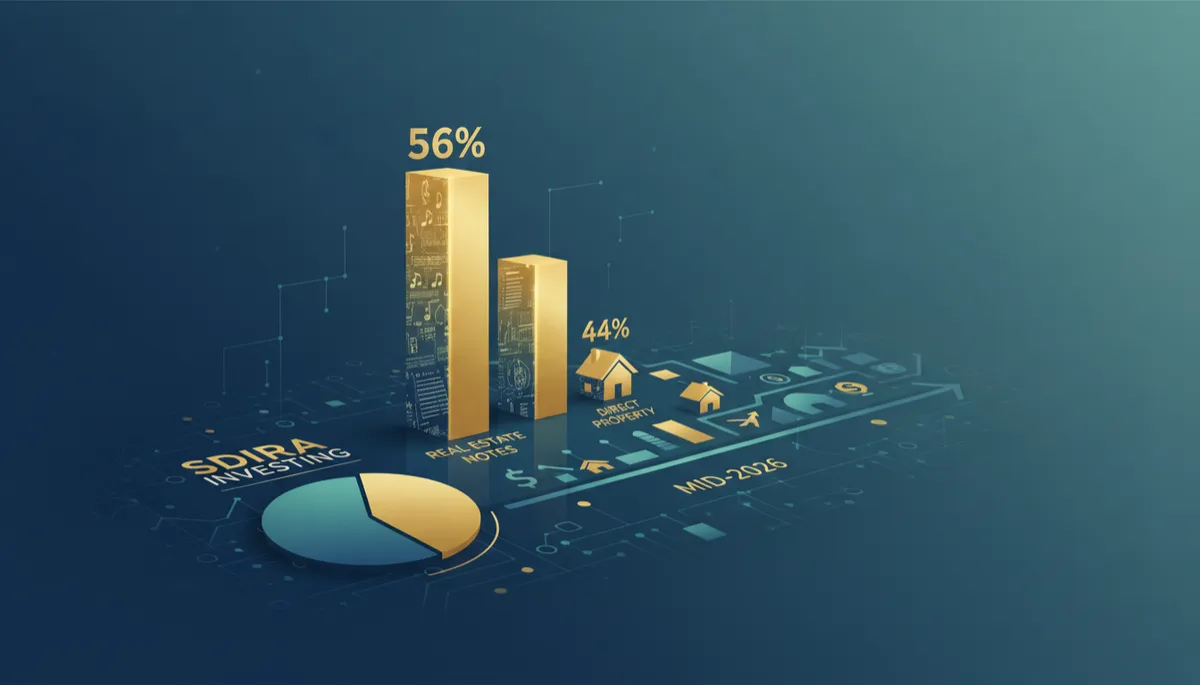
Real Estate Notes Lead SDIRA Investments 2026
Real Estate, Self-Directed IRAs, Retirement Investing
Published: August 23, 2026
Real Estate Notes Now Dominate SDIRA Investing — Here’s What the Latest Industry Data Shows
New industry research confirms a decisive shift inside self-directed IRAs: real estate notes now account for the majority of SDIRA real estate purchases, outpacing direct property ownership. For self-directed investors evaluating opportunities in mid-2026, understanding why this is happening—and what it means for risk, return, and portfolio design—is essential.
The New Reality: Notes Represent 56% of SDIRA Real Estate Purchases
IRAR Trust’s latest market report, based on 1,997 SDIRA real estate transactions completed in 2025, shows that real estate notes accounted for 56% of purchase activity, while direct real property purchases made up the remaining 44% (IRAR Trust, 2025 SDIRA Real Estate Investor Trends). In other words, more than half of SDIRA real estate deals are now structured as notes—private loans, promissory notes, and similar debt instruments secured by real estate—rather than outright ownership of property.
This is a notable change in a segment where “owning the property” has long been the default vision of real estate investing. The asset class itself remains strong; what is evolving is the preferred structure for holding that exposure inside retirement accounts. STRATA Trust and Kiplinger both highlight real estate as a leading choice for self-directed investors, but the internal mix has shifted decisively toward debt-based strategies inside IRAs.
“We’re not seeing investors abandon real estate. We’re seeing them reframe their role—from landlord to lender.”
— Industry observation based on recent SDIRA transaction data
Why Notes Are Outpacing Direct Property Ownership
Several structural and market factors help explain why real estate notes have moved ahead of direct property in SDIRA activity:
- Income orientation: Notes typically provide contractual interest payments at defined rates and schedules. For retirement-focused investors, this predictable cash flow can be easier to underwrite than variable rental income, vacancies, and operating expenses associated with owning property directly.
- Operational simplicity: With a note, the SDIRA generally holds a loan rather than a physical asset. That means no property management, no direct dealing with tenants, and fewer ongoing decisions about repairs, insurance, or leasing strategies. Custodians and administrators often find it more straightforward to process note investments than to manage the documentation and complexities of multiple properties.
- Risk framing and collateral: Properly structured, real estate notes are secured by underlying property. American IRA and Midatlantic IRA both emphasize that this collateralization, combined with underwriting standards and defined repayment terms, can provide a disciplined framework for risk management—especially important in a retirement account where capital preservation matters.
- Alignment with higher-rate environments: In a period of elevated interest rates, new private loans can be originated at yields that may compare favorably with cap rates on direct property investments. For many SDIRA investors, it can be more attractive to earn a higher fixed rate on a note than to assume landlord responsibilities for a similar or lower net yield.
Together, these factors help explain why notes are now outpacing direct property ownership in SDIRA transaction counts, even though both approaches remain central to self-directed real estate strategies.
What Mid‑2026 Market Conditions Look Like for Note Investors
As of mid‑2026, the broader backdrop for real estate notes inside SDIRAs is shaped by a combination of rate dynamics, liquidity needs, and ongoing interest in alternatives. Several data points from the secondary mortgage note market illustrate the current environment.
FIXnotes reports that approximately $224.5 million in notes have traded on its platform since 2020. More importantly for today’s buyers, the 90‑day average price‑to‑unpaid principal balance (UPB) sits around 32.8% as of August 20, 2026, down from 41.9% a year earlier. In practical terms, this means secondary‑market buyers are acquiring notes at roughly one‑third of face value, on average.
Monthly snapshots underscore the volatility and opportunity in this space. For example, July 2026 saw 32 notes trade with $879,000 in UPB at an average price of 37.1% of balance, while June recorded 37 notes and $391,000 in UPB at 34.5%. These discounts reflect a market where sellers are willing to part with notes at reduced prices—often due to their own liquidity needs or changing risk appetites—creating potential yield and equity‑capture opportunities for patient SDIRA investors who can hold to resolution.
How This Data Translates into Practical Implications for SDIRA Portfolios
For self-directed IRA investors, the combination of 56% of SDIRA real estate purchases now being notes and a secondary market trading at meaningful discounts has several implications for portfolio construction and risk management.
- Yield potential versus complexity: Discounted note purchases can offer attractive yield‑to‑maturity profiles, especially when acquired significantly below UPB. However, non‑performing or distressed notes require specialized workout strategies, legal coordination, and realistic timelines. Within an IRA, where distributions and required minimum distributions (RMDs) must be planned, investors should match note strategies to their time horizon and administrative capacity.
- Secured versus unsecured exposure: Industry data from uDirect IRA suggests that secured notes and unsecured notes together account for a meaningful share of SDIRA activity. In the current environment, many investors and custodians emphasize secured, collateral‑backed structures as a way to balance return potential with downside protection. Evaluating loan‑to‑value ratios, borrower quality, and lien position is critical.
- Diversification within real estate: The rise of notes does not eliminate the role of direct property ownership. Instead, it creates an additional tool. Some SDIRA investors are blending strategies—holding a core of stabilized rental property while allocating a defined portion of their account to well‑underwritten notes for income and opportunistic upside. This can help spread risk across different parts of the real estate capital structure.
- Fit with evolving alternative‑asset allocations: Broader surveys show that real estate remains the most popular alternative in SDIRAs, but investors are becoming more deliberate about total alternative exposure. As knowledge increases, many are moderating allocations toward advisor‑recommended ranges. In this context, notes offer a way to keep real estate exposure while fine‑tuning duration, cash‑flow profile, and risk level inside the IRA.
Key Considerations Before Increasing Your Note Allocation
The data make a strong case that real estate notes have become a central pillar of SDIRA investing. However, they are not a one‑size‑fits‑all solution. Before expanding exposure, self-directed investors should consider:
- Due diligence capacity: Assess whether you have the expertise—or access to professionals—to evaluate collateral value, documentation, borrower history, and servicing arrangements. Note investing is highly document‑driven.
- Custodian requirements: Each SDIRA custodian has its own processes and standards for approving private lending and note transactions. Understanding timelines, fees, and documentation standards in advance can help avoid delays and unexpected costs.
- Regulatory and tax rules: As with any SDIRA investment, prohibited transaction rules, disqualified persons, and fair‑market‑value reporting must be respected. Professional guidance can help ensure that creative note structures do not inadvertently create compliance issues.
What the Shift Toward Notes Means Going Forward
The fact that real estate notes now represent 56% of SDIRA real estate purchase activity, outpacing direct ownership, signals a maturation of how self-directed investors use real estate in their retirement planning. Rather than relying solely on being a landlord, more investors are positioning their IRAs as lenders—seeking contractual income, collateral protection, and the potential to buy at discounts in an environment where capital is valued.
For SDIRA investors in mid‑2026, the opportunity is clear but nuanced. Real estate notes can play a powerful role in building income‑oriented, risk‑aware portfolios, particularly when rates remain elevated and secondary‑market discounts persist. The differentiator will not be access to deals, but the quality of underwriting and portfolio design. The challenge—and the differentiator—will be the quality of underwriting, the discipline of structure, and the alignment of each note investment with long‑term retirement objectives.
